I'm "Blacklisted".Can I Still Get a Loan in Malaysia?
There is no official blacklist. Bank Negara Malaysia states that CCRIS doesn't blacklist anyone; each bank decides using its own policy. When people say they're "blacklisted", they usually mean one of five records: recent late payments, a Special Attention Account (SAA), an AKPK plan, a court case or trade reference in CTOS, or bankruptcy. Some of these can be fixed in months, others take longer, and bankruptcy usually has to be resolved first.
STS Wealth Care team
Last updated 3 min read
"Blacklist" is the word everyone uses, but it hides very different situations. What you can do depends on which record a bank is actually seeing.
1. Recent late payments in CCRIS
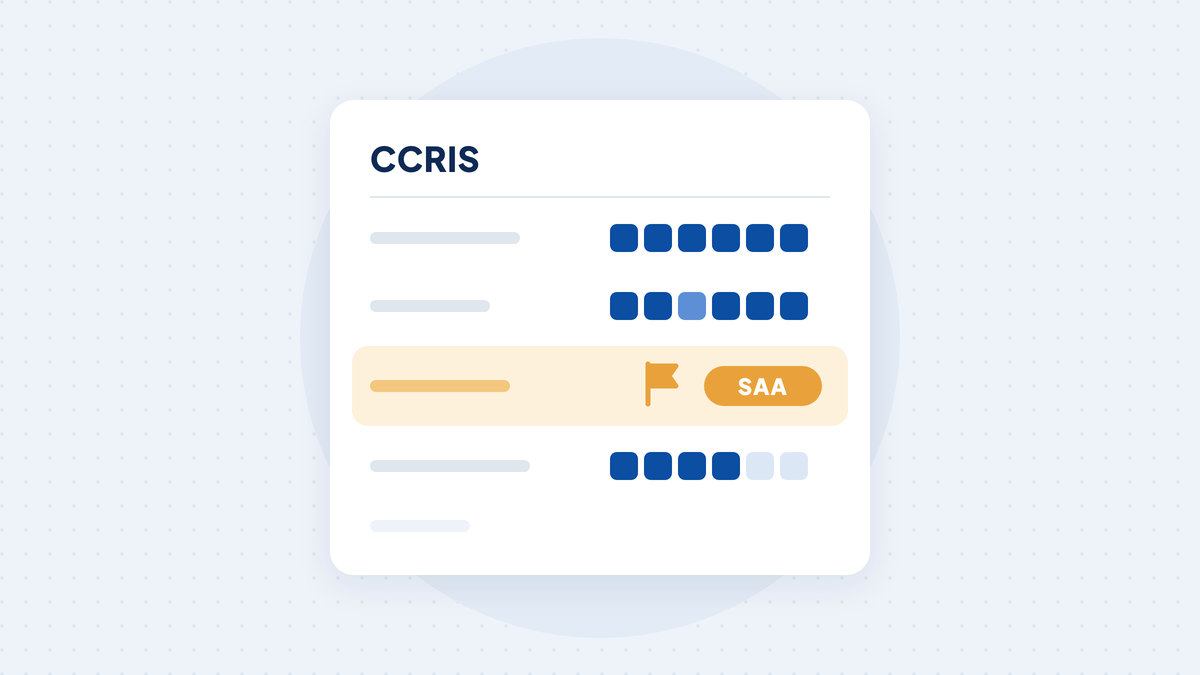
CCRIS shows the last 12 months of repayment for each account. Numbers like 1, 2 or 3 mean you were that many months behind.
- What helps: clear the arrears, then pay every account on time. Each clean month improves the 12-month picture.
- Outlook: often the easiest to fix. Some banks will look again after a few clean months.
2. A Special Attention Account (SAA)
An SAA is a loan the bank has marked as impaired and is trying to recover. Most banks won't approve new credit while it is outstanding.
- What helps: contact that bank for a settlement or restructuring, get it in writing, and check that CCRIS is updated afterwards.
- Outlook: much harder until it is settled. See What is SAA in CCRIS?.
3. You're on an AKPK plan
An AKPK debt management plan shows in your CCRIS while you are on it. Most banks are cautious until the plan is completed.
- What helps: keep paying the plan; once it's finished, keep the completion letter.
- Outlook: see How long after AKPK can I get a loan?.
4. A court case or trade reference in CTOS
CTOS can show court cases and, if a company reported it, unpaid bills such as a telco or trade reference.
- What helps: settle the amount, ask the company for a settlement letter, and ask it to update or withdraw the trade reference. Some banks look at these closely even after payment.
- Outlook: depends on the bank and how old the record is.
5. Bankruptcy
If you are an undischarged bankrupt, banks generally cannot lend to you.
- What helps: check your status with the Insolvency Department (MdI) and work on getting discharged first.
- Outlook: a loan is not realistic until the bankruptcy is resolved.
Where to start
- 1.Check your own CCRIS for free. Here's how to check your CCRIS.
- 2.Find which of the five records above applies to you. It may be more than one.
- 3.Fix the ones you can before applying. Each application shows in your CCRIS.
Watch out for "blacklist pun boleh" offers
Anyone who promises a guaranteed loan despite your record, or offers to delete records from CCRIS or CTOS for a fee, is very likely a scam. Accurate records can't be removed by paying an agent. Read how to spot a fake loan agent.
STS Wealth Care is a loan advisory consultant, not a bank or lender. We read your CCRIS and CTOS with you, tell you honestly which records banks will focus on, and what to fix first. We don't charge an upfront fee, and approval is always the bank's decision.
Quick questions
- Is there a list of blacklisted people at Bank Negara?
- No. BNM states that CCRIS is not a blacklist and doesn't rate borrowers. It only shows the facts banks report, and each bank decides using its own policy.
- Can an agent remove my bad record?
- No. An accurate record stays until the reporting bank or company updates it, for example after you settle. Paying someone to "clean" your record is a common scam.
- Can I borrow from a licensed moneylender instead?
- Licensed moneylenders (registered with KPKT) may consider profiles that banks don't, but the cost is usually much higher. Check the licence first, read the agreement carefully, and only borrow what you can repay.
Want us to look at your situation?
Send us a WhatsApp message. We reply within 24 hours, Monday to Friday, 10:00am to 5:00pm. No upfront fee, and asking doesn't mean you have to apply.
Free download
10-point pre-application checklist
Check these 10 things before you apply for any loan. Leave your name and number and the PDF is yours right away.
- Check your eCCRIS and CTOS yourself first
- Work out a rough DSR
- Spot upfront-fee scams
This article is general information, not financial or legal advice. STS Wealth Care is a loan advisory consultant, not a bank, lender or licensed financial advisor. Approval, rates and amounts are always decided by the bank or financial institution.